Home Sales Have Not Improved at All Despite the Lowest Mortgage Rates in a Year
Pending home sales and applications for mortgages to purchase a home are near historic lows, and lower mortgage rates have not stimulated demand.
By Wolf Richter for WOLF STREET.
Pending home sales – tracking the number of contracts signed – were unchanged in September from August, and were down 0.9% from the collapsed levels a year ago, seasonally adjusted.
Pending home sales compared to the Septembers in prior years:
- 2024: -0.9%
- 2023: +1.2%
- 2022: -8.3%
- 2021: -35.1%
- 2020: -41.1%
- 2019: -30.7%.
The new normal? This completes the third year in a row that pending sales have zigzagged along record low levels in the data by the National Association of Realtors, which goes back to July 2010. There simply has been no improvement for three years (historic data via YCharts):
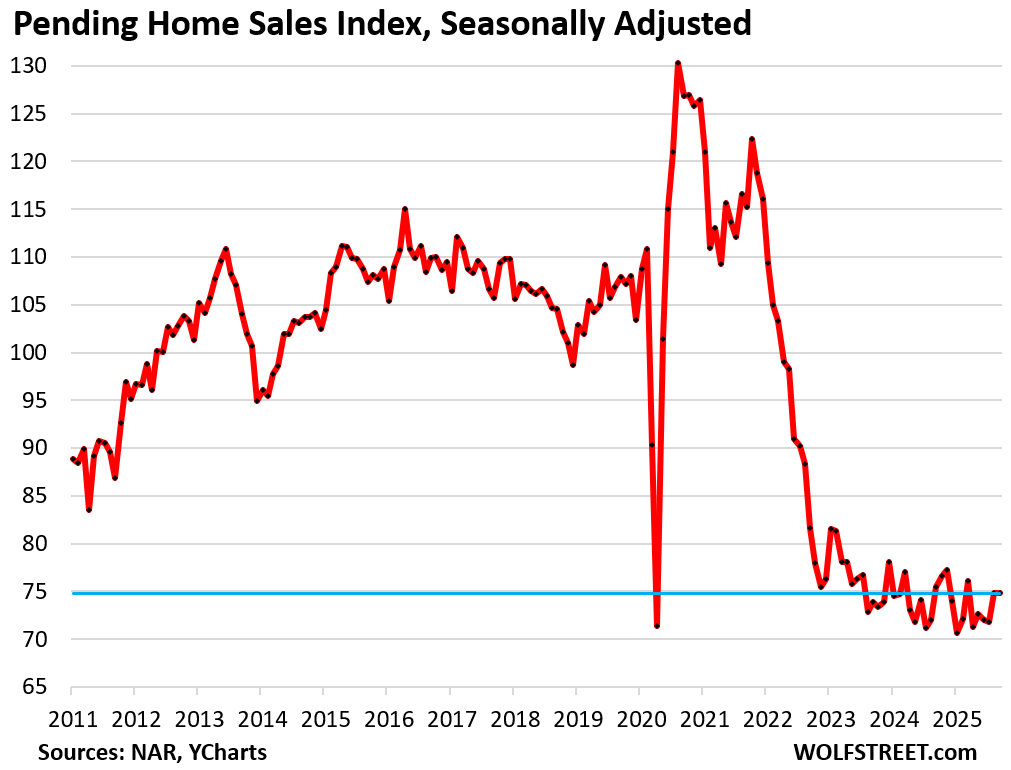
Pending sales are based on contract signings and track deals that haven’t closed yet and could still get canceled because buyers cannot afford homeowner’s insurance, or cannot sell their own home, or for other reasons.
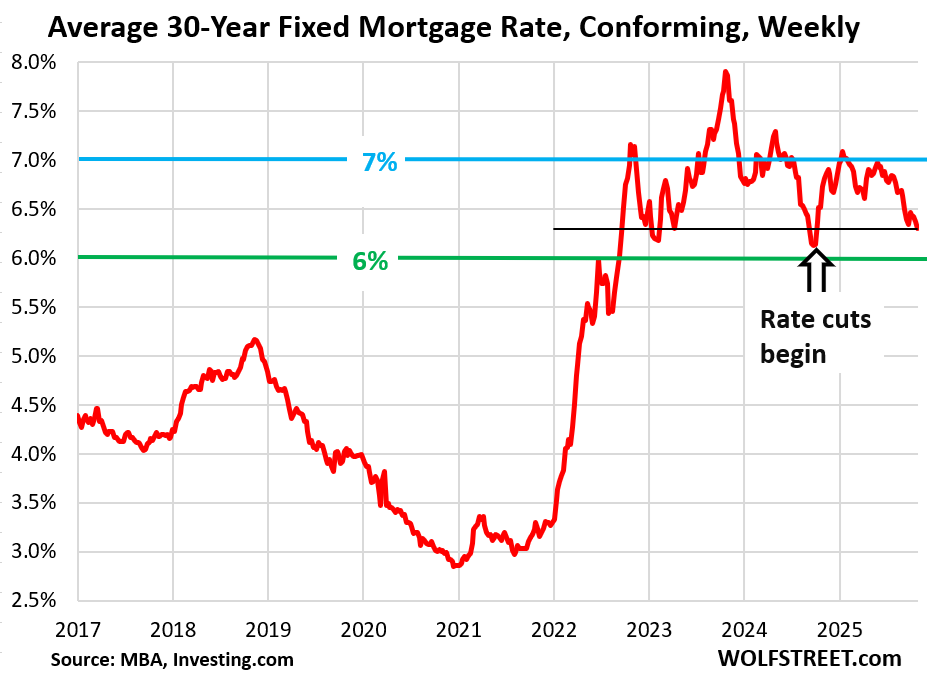
But the average mortgage rate for conforming 30-year fixed mortgages declined by 7 basis points to 6.30% in the latest week, the lowest level in a year, according to the Mortgage Bankers Association today.
Since the end of May, mortgage rates have dropped by 68 basis points (from 6.98%). Yet home sales have continued to zigzag along the record low levels.
Mortgage rates, according to the MBA’s measure, bottomed out in September 2024 at 6.13%, just before the Fed started cutting interest rates.
But this range between 6% and 7% was at the low end of the historic range before 2008 and before QE – including the Fed’s purchases of MBS – which distorted everything.
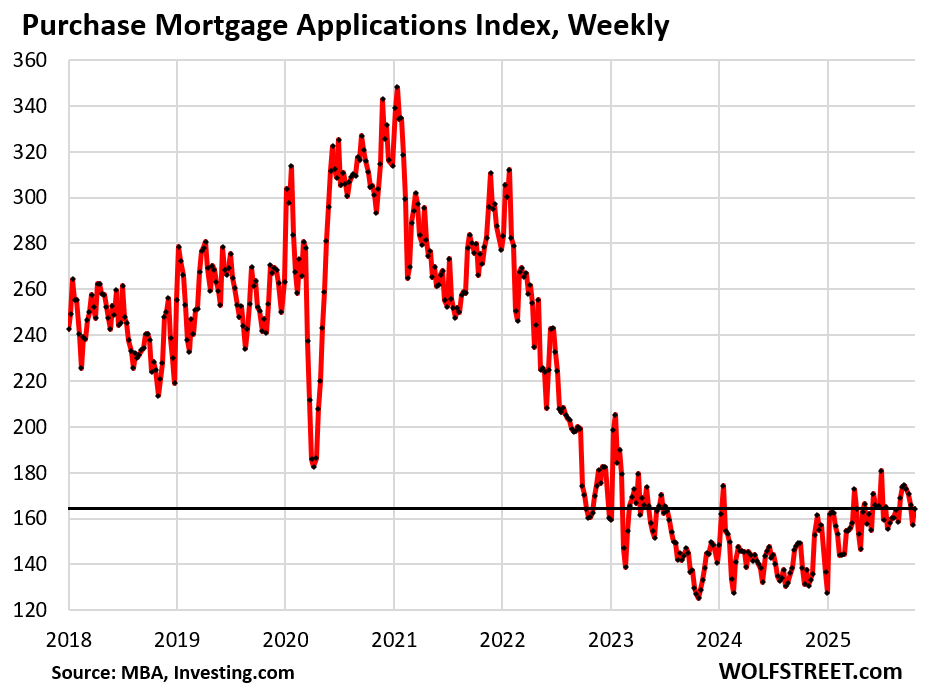
Applications for mortgages to purchase a home in the latest week ticked up from the drop of the prior week, but not enough to make up for all of the drop, according to data from the MBA today.
These purchase mortgage applications are an indicator of home sales in the near future.
Demand for mortgages to purchase a home began to plunge over three years ago and has been wobbling along these very low levels ever since.
Compared to the same week in 2019, purchase mortgage applications were down by 34%, the new normal – despite the much lower mortgage rates. The immensely hyped theme that lower mortgage rates would unleash waves of demand just hasn’t panned out.
Pending home sales by region.
A map of the four Census Regions is posted in the comments below.
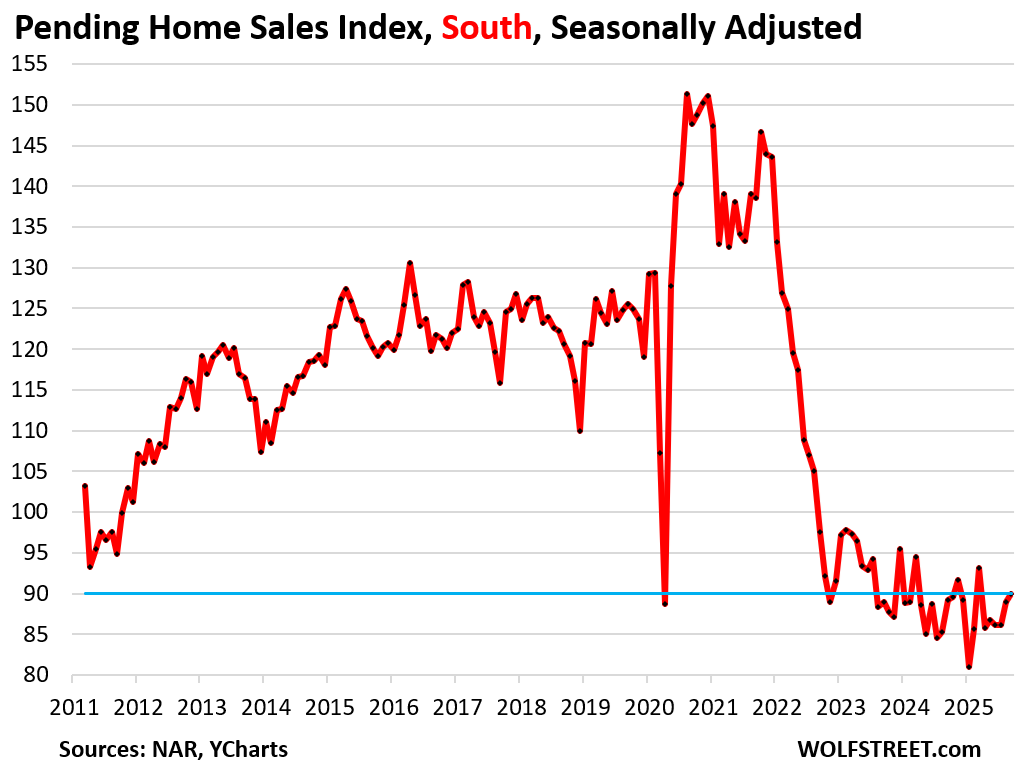
In the South, pending sales ticked up 1.1% in September from August, and by 0.9% year-over-year, seasonally adjusted, according to the NAR today.
Compared to the Augusts of prior years:
- 2024: +0.9%
- 2023: +1.1%
- 2021: -35.0%
- 2020: -39.1%
- 2019: -28.3%.
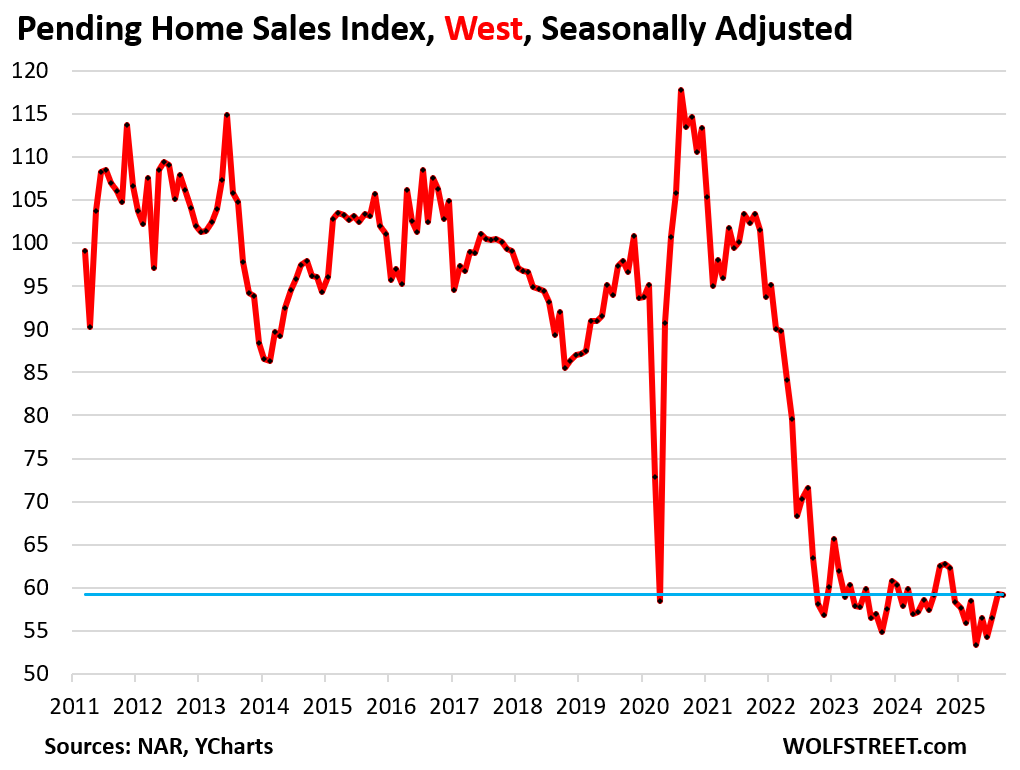
In the West, pending sales dipped by 0.2% in September from August, and were down 5.3% year-over-year.
Compared to the Septembers of prior years:
- 2024: -5.3%
- 2023: +3.9%
- 2021: -42.1%
- 2020: -47.8%
- 2019: -39.5%.
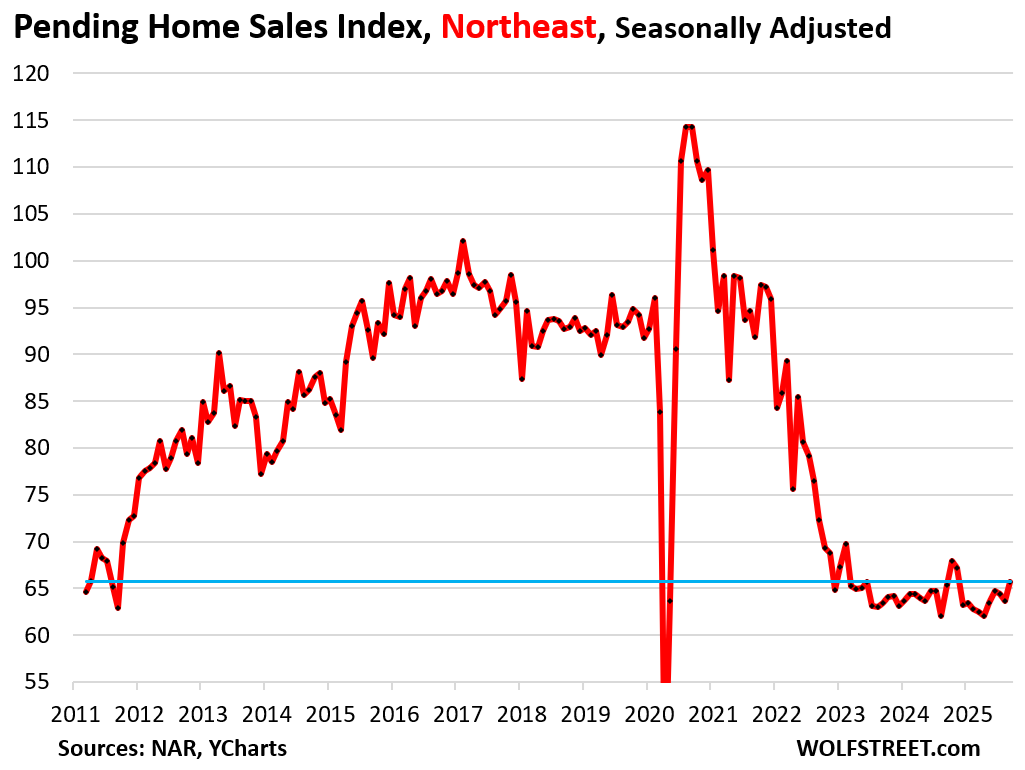
In the Northeast, pending sales rose by 3.1% month-to-month, and were a hair higher than a year ago, seasonally adjusted.
Compared to the Septembers of prior years:
- 2024: +0.5%
- 2023: +3.5%
- 2021: -28.5%
- 2020: -42.5%
- 2019: -29.7%.
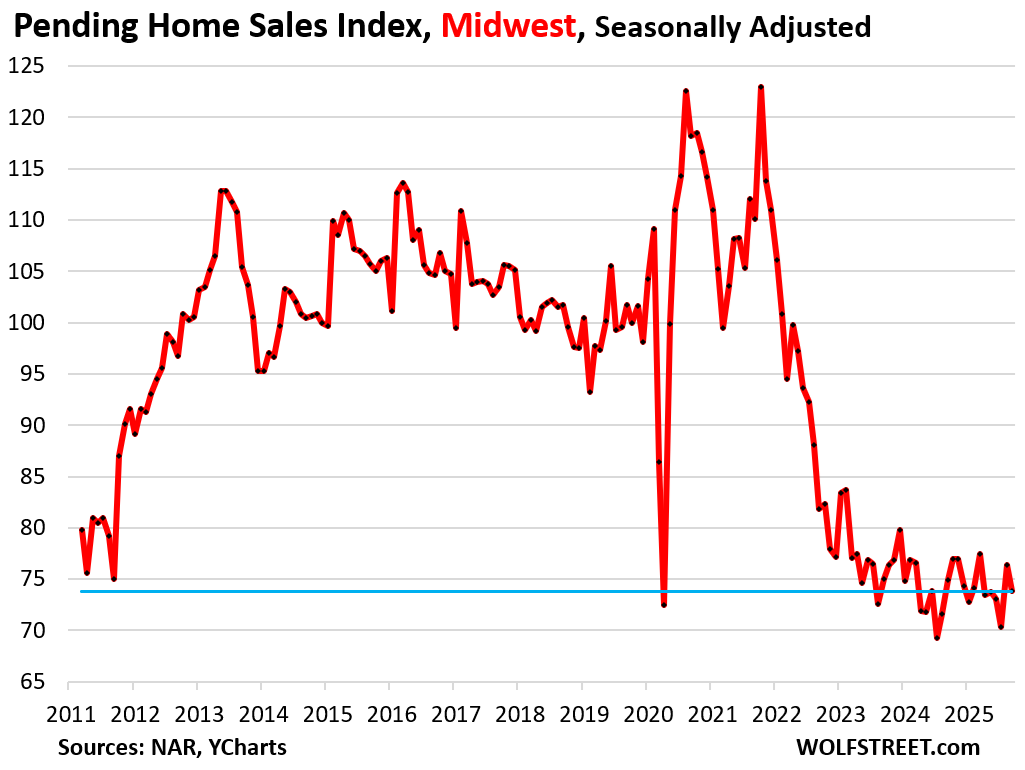
In the Midwest, pending sales fell by 3.4% in September from August and by 1.5% year-over-year.
Compared to the Septembers of prior years:
- 2024: -1.5%
- 2023: -1.6%
- 2021: -33.0%
- 2020: -37.6%
- 2019: -27.4%.
Clearly, the market is not thawing. Prices are still too high after they exploded by 40%, 50% or even 70% in specific markets over the course of 2-3 years.
They’d exploded because the Fed had forced mortgage rates down via massive purchases of Treasury securities and MBS, to where mortgage rates dropped below 3% while inflation was spiking toward 9%, and borrowing at 3% with inflation at 5%, 6%, 7%, and then higher was free money, better than free money, and when money is free, prices don’t matter, and home prices exploded.
But those prices don’t make economic sense, they’re too high, they’ve destroyed demand. And in some markets, they have started to come down fairly hard:
The 23 Bigger Cities where Condo Prices Dropped by 12% to 28% through September
The Cities Where Condo Prices Are Now Below their Housing Bubble Peaks 20 Years Ago
Enjoy reading WOLF STREET and want to support it? You can donate. I appreciate it immensely. Click on the mug to find out how: